

ATM Cash Advance・Instant Money

- 14.20K Reviews
- 4.5
- Downloads
- 1,000,000+
Our take on ATM Cash Advance・Instant Money from Appgk
I approached ATM Cash Advance・Instant Money as a practical finance app rather than something I would open for entertainment. Its promise is straightforward: help me find ways to manage everyday cash needs, build saving habits, and request an advance when an unexpected expense appears. After spending time with it, my main question became less “does it work once?” and more “would I still keep it installed when the first-week curiosity disappears?”
My answer is qualified but positive. The app can earn a lasting place on a phone if I use it as a small part of a broader money routine. It is most useful when I treat cash advances as an emergency bridge, not as extra income, and when I regularly check the terms before accepting anything. That distinction matters because an easy application flow can make short-term borrowing feel more harmless than it really is.
ATM Cash Advance・Instant Money is a free finance app from ATM.com, Inc. It has an Everyone age rating, works on Android eight and later, and its current version is 2.139.0. The app has built a sizeable audience, with more than a million installs, an average rating of 4.5 from roughly fifty-four thousand ratings, and about fourteen thousand written reviews. Those figures suggest that many people find the basic idea useful, although popularity alone should never replace reading the details of a financial offer.
From first-week convenience to a lasting money habit
Why the first few days feel useful
The strongest first impression is the app’s focus. Instead of presenting itself as a full bank replacement, it centers on cash access and saving-related routines. That narrow purpose makes it easy to understand what I am supposed to do: look for available options, review the information shown, and decide whether the tool fits the immediate situation.
Best Parts of ATM Cash Advance・Instant Money
Things to Keep in Mind About ATM Cash Advance・Instant Money
For someone whose checking account is temporarily short before payday, that clarity can be reassuring. A sudden prescription, a necessary repair, or a bill arriving at an awkward time can create a problem even when the household budget is normally stable. In that kind of moment, an app that brings the process into one place may feel less intimidating than calling several providers or searching through unrelated financial products.
The first-week appeal also comes from the combination of two different ideas: access to an advance and encouragement to save. Those goals can pull in opposite directions. Borrowing solves a present shortage, while saving is meant to prevent future shortages. I like that the app places both concepts in the same experience because it can prompt me to think beyond the immediate request. Still, the saving side only becomes meaningful if I return often enough to act on it.
News and Features Related to ATM Cash Advance・Instant Money

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A realistic example is a user who notices that a utility payment will clear before their next paycheck. Rather than immediately accepting an advance, I would first use the app to understand the amount available, the repayment expectations, and the total obligation. If the gap is small and repayment is certain, the tool may be reasonable. If the payment would leave me short again next month, the app is revealing a recurring budget problem, not solving it.
What I would check before requesting money
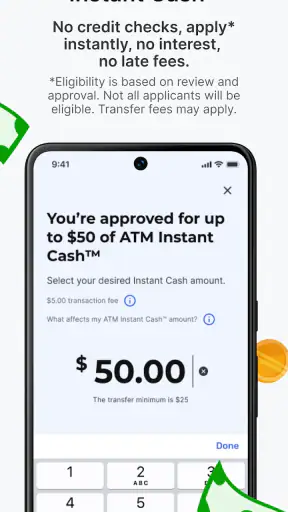
The phrase “no credit check” can sound especially attractive when someone is under pressure. I would not interpret it as “free money” or as proof that the transaction carries no consequences. Before confirming anything, I would look carefully at the amount received, the amount due, the timing, and every disclosed fee or condition. If the information is difficult to understand, I would stop rather than rely on the speed of the process.
Don't want to read the full review?
This is one of the most important practical habits with a cash-advance app: separate approval convenience from affordability. A request can be easy to complete and still be a poor decision for my budget. I would also avoid borrowing to cover a recurring subscription, routine shopping, or another expense that will appear again next week. An advance is better suited to a genuinely temporary gap than to a permanent mismatch between income and spending.
Another useful first-week test is to see whether I can use the app without feeling pushed into a decision. I would read each screen slowly, take note of repayment information, and close the process if I need time to compare alternatives. That approach turns the app into a research tool instead of an automatic borrowing button.
Screenshots
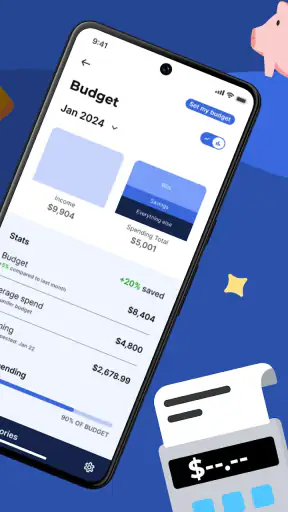
Where it fits beside familiar alternatives
Compared with a traditional bank overdraft, this app may feel more direct and easier to explore from a phone. A bank, however, may offer a more established relationship, clearer account history, or other ways to handle a temporary shortage. The better choice depends on the actual cost and repayment structure, not on which interface feels faster.
Compared with a credit card, a cash advance may avoid adding another revolving credit account, but it does not automatically make the transaction cheaper or safer. A credit card can be useful for someone who already has a disciplined repayment plan and understands their interest terms. For someone trying to avoid revolving debt, neither option should be used casually.
Compared with asking a trusted person for help, the app offers privacy and independence, but a personal loan may come with more flexible timing. Compared with a payday lender, the app may seem more convenient and less intimidating, yet I would still compare the complete obligation rather than judging by the brand or mobile design. The key advantage here is access and organization; the key risk is that convenience can shorten the time I spend thinking.
The first-month question: does saving become automatic?
The saving angle is where the app’s long-term value has to prove itself. Opening a finance app once does not change my behavior. I would get more from it by choosing a fixed weekly check-in, reviewing whether I actually needed an advance, and moving any realistic amount toward a buffer when possible. Even a small reserve can reduce the temptation to borrow for the next minor surprise, but only if the habit survives beyond the initial setup.
I would keep a simple note outside the app showing why I needed money, how much I requested, and whether repayment affected the following pay cycle. This is a non-obvious but useful workflow because the app may make each request look isolated. My own record shows the pattern. If I see the same type of shortfall repeatedly, the correct next step may be changing bill dates, trimming a fixed expense, or seeking budgeting help rather than making another request.
That personal record also helps me judge whether the app deserves permanent space. If I use the saving tools consistently and rarely need an advance, it may be contributing to better financial resilience. If I open it only during emergencies, it remains a backup utility rather than a daily money manager. Both uses are valid, but they should not be confused.
Maintenance: what I would keep watching
Finance apps require more maintenance than their simple screens suggest. I would review the current app version after updates, check that my personal details remain accurate, and read any revised explanations before starting a new transaction. The listed release date is October 26, 2020, so the product has had time to evolve, but longevity does not mean I can skip checking current conditions.
I would also maintain a separate calendar reminder for repayment. Relying only on memory is risky when income, bills, and advance timing overlap. A reminder gives me the chance to keep enough money available and avoid turning a one-time bridge into a larger problem. This is particularly important for users who have irregular income or several payments clustered around the same week.
Privacy is another maintenance task. I would review what information the app asks me to provide and make sure I understand why it is needed before continuing. I would keep the device protected with a screen lock and avoid using a shared phone for financial activity. These steps are not glamorous, but they matter more than the novelty of instant access.
Finally, I would periodically compare the app with my alternatives. A finance tool can remain installed long after it stops being the best fit. If my bank introduces a cheaper overdraft option, my employer offers an earned-wage program, or my savings buffer becomes sufficient, I would reassess rather than keep borrowing out of habit.
Where fatigue begins
The first source of fatigue is decision pressure. When I am worried about a bill, a fast application can encourage me to focus on receiving money instead of understanding the repayment impact. Repeating that process can create a cycle in which each pay period begins with money already committed. The app cannot fix that cycle by itself, and I would not expect it to.
A second source is the need to revisit financial details. Terms, eligibility, and available amounts may depend on the individual situation and the current offer shown in the app. That means I should not assume that a previous experience will be identical next time. For a returning user, this can feel repetitive, but it is necessary. Financial products deserve fresh attention whenever I make a new decision.
A third issue is emotional fatigue. Having an advance option visible on my phone can make borrowing feel like part of normal spending. I would reduce that temptation by removing notifications I do not need, avoiding casual browsing when I am bored, and opening the app only with a specific purpose. The most helpful finance habit is often creating a pause between feeling anxious and accepting a solution.
There is also a practical limitation for users seeking a complete financial dashboard. This app is focused on cash advances and saving, so I would not choose it as my only tool for detailed investing, comprehensive account aggregation, or long-term financial planning. A bank app, spreadsheet, or dedicated budgeting service may be better for seeing the full household picture. Keeping those roles separate can make the app more useful rather than less.
Who should use it and who should skip it
I think it suits adults who occasionally face a short cash gap, can verify their repayment ability, and want a mobile-first way to explore an advance while also thinking about saving. It may also help someone who wants a reminder that emergency borrowing should be paired with building a small reserve. The free download lowers the barrier to trying the service, but the financial decision itself still needs care.
I would skip it if I already know that repayment would require another advance. I would also avoid it if I am looking for a long-term debt solution, help with serious financial hardship, or a replacement for professional advice. Someone with unstable income should be especially cautious because the next repayment may arrive before the next reliable paycheck.
It is not the right choice for a person who dislikes checking terms, tracking dates, or comparing total costs. The convenience only works in my favor when I remain actively involved. If I want a set-and-forget savings account, a traditional savings product may be more appropriate. If I need a full budget, I would pair this app with a tool designed for income and spending analysis rather than expecting one focused service to do everything.
My long-term verdict after the novelty fades
After the initial appeal wears off, I see ATM Cash Advance・Instant Money as a useful backup with the potential to support a modest saving routine. Its lasting value depends almost entirely on how I use it. As an occasional emergency bridge, it can be practical. As a repeated way to make every payday stretch, it can become a warning sign that my budget needs a different solution.
The strongest long-term workflow is simple: open the app only for a defined purpose, read the complete offer, compare it with my bank and other realistic options, set a repayment reminder, and record what caused the cash gap. Then I would use the next month to reduce the chance of repeating it. That process turns a quick finance app into part of a more responsible system.
My recommendation is therefore measured. I would keep it installed if I wanted occasional access to a cash-advance option and was willing to monitor the consequences closely. I would not make it the center of my financial life, and I would never treat “no credit check” as a substitute for affordability. Its real strength is convenience paired with a chance to build better habits; its real weakness is how easily convenience can become routine borrowing.
For the right user, that balance is enough to justify keeping it on the phone. For anyone hoping for effortless financial stability, it is not. The app can help me handle a temporary moment, but the lasting solution still comes from maintaining a buffer, understanding my obligations, and making sure next month is not dependent on another advance.
ATM Cash Advance・Instant Money FAQ
What is ATM Cash Advance・Instant Money, and how does it work?
ATM Cash Advance・Instant Money is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account and providing the requested personal and financial information, the app may display available advance options, fees, repayment terms, and estimated delivery times. Approval is not guaranteed, and availability can depend on your location, credit profile, income, and the app’s lending partners.
How much does ATM Cash Advance・Instant Money cost to use?
The total cost can vary depending on the amount requested, repayment period, eligibility, and the specific offer shown in the app. Before accepting an advance, carefully review any service charges, subscription fees, transaction fees, interest, tips, or late-payment penalties. Some financial apps advertise quick access to money but may have recurring membership costs, so check the final repayment amount and cancellation terms rather than relying only on promotional wording.
How quickly can I receive money after approval?
Delivery time depends on the approval process, your bank, the selected transfer method, weekends or holidays, and whether you choose a standard or expedited option. Some users may see funds deposited quickly, while others may experience delays caused by identity verification or banking procedures. The app should show an estimated arrival time before confirmation, but this estimate should not be treated as a guarantee.
What information and permissions does the app require?
To evaluate an application and provide its services, ATM Cash Advance・Instant Money may request information such as your name, contact details, identification data, employment or income details, bank information, and repayment account. Review the privacy policy and permission requests before continuing. Only provide accurate information through official app screens, and avoid sharing passwords, security codes, or banking credentials outside secure, verified channels.
Is ATM Cash Advance・Instant Money safe and available to everyone?
The app may use security measures to protect account and financial information, but no digital financial service is completely risk-free. Confirm that you are downloading the official version from a trusted app store and check the developer, reviews, privacy disclosures, and customer-support details. Eligibility, age requirements, geographic availability, and approval standards may differ, so read the terms carefully and borrow only what you can repay.











